"Give me a place to stand, and I will move the earth."
— Archimedes, on the lever
In May 2026, two of the leading AI labs did something that would have sounded absurd a year earlier. They became consultancies.
On May 11, OpenAI launched the OpenAI Deployment Company with more than $4 billion behind it. Its backers include TPG, Advent, Bain Capital, Brookfield, Goldman Sachs, SoftBank and Warburg Pincus. It bought Tomoro, an AI engineering firm, to give it 150 forward-deployed engineers on day one.1 Ten days later, a new venture formed by Anthropic, Blackstone and Hellman & Friedman, with about $1.5 billion of reported backing, made its first acquisition: Fractional AI, an applied-AI services firm, as its operating core. Its stated job is to help mid-sized businesses rebuild their operations around Claude, starting with Blackstone's own portfolio companies.23
The rest of the market had already been moving the same way. Accenture agreed to buy NeuraFlash to bring agentic AI to its Salesforce clients.4 Carlyle bought the data and AI consultancy Adastra.5 Cinven entered exclusive talks for Artefact.6
Read the cap table of those deals and you are reading a list of the most sophisticated capital on earth. All of it has reached the same conclusion. The bottleneck in the intelligence economy is no longer the model. It is getting the model to do real work inside real companies.
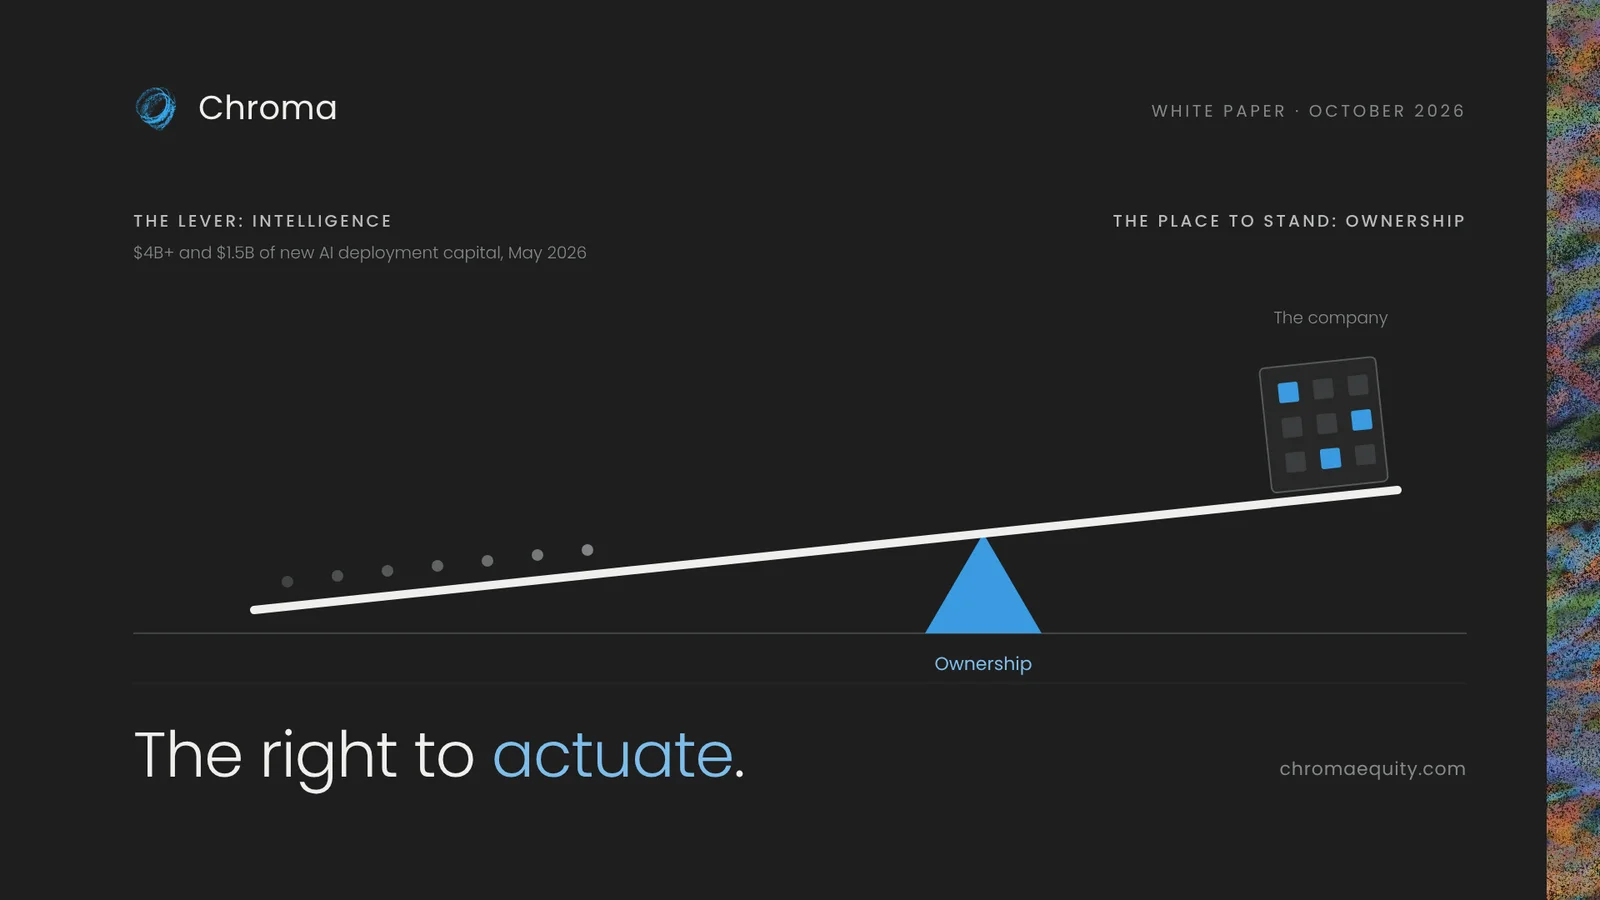
Our position. They are right about the bottleneck. We think they have bought the wrong side of it. A company with years of unmeasured, un-systematised work inside it is a portfolio of options that AI has just made exercisable: prices that were never set properly, schedules that were never optimised, contracts that were never written, data that was never collected. Exercising those options takes four things: access to the company's ground truth, the authority to change how it runs, the engineers to do it, and the patience to see whether it worked. A deployment company brings the engineers and rents the rest for the length of an engagement. It is paid a fee to exercise options that belong to someone else. The owner holds the options. Chroma owns the companies it rebuilds, takes control with little or no debt, puts its own engineers inside, and keeps the payoff. And because we own the results, not just the project, every company teaches us where intelligence pays next. The labs have built extraordinary levers. Archimedes understood that the lever was never the scarce part. The place to stand was. In the intelligence economy, that place is ownership.
A company is a bundle of options
Finance has had a name for this since 1977, when Stewart Myers pointed out that much of a company's value lies not in the assets it uses today but in its opportunities to invest and change tomorrow. He called them real options.8 An option is worth something only if it can be exercised. For most of the history of small business, many of these options could not be.
Consider what sits inside a typical 40-person inspection or field-service company:
- A price list nobody has revisited in years. The option to price each job from real data has always existed. Nobody had the time or the numbers to exercise it.
- A schedule run from one person's memory. The option to route every technician optimally has always existed. Doing it by hand was impossible.
- Thousands of one-off jobs. The option to turn them into service contracts has always existed. Nobody had the data to know which customers would want one.
- Decades of records in binders and inboxes. The option to learn from them has always existed. No one could read them all.
This is what the investor who writes as illiquid calls latent complexity: companies, and whole economies, that are portfolios of real options AI makes exercisable. The question it poses to every allocator is the right one. Where is the most valuable uninstrumented complexity, and who has the right to access it and the ability to act on it?7
Our answer to the first half is specific. The largest pool of uninstrumented complexity in America sits inside its owner-run businesses. Only about 20% of US businesses used AI in May 2026, against 37% of firms with 250 or more employees, and use was flat among the smallest.10 About 6 million small businesses face an ownership exit by 2035, more than a million of them viable for sale.11 Those options have been sitting unexercised for decades. They are about to change hands.
The second half of the question, who has the right to act, is where the money will be made.
The four things it takes to exercise an option
A model can identify an opportunity in seconds. Turning it into profit requires four things, and the model supplies none of them.
Access. The ground truth of the business: its jobs, prices, customers, margins and failures. Without it, a model is guessing.
The right to actuate. The authority to change a price, rewrite a contract, redesign a workflow or reassign a team. Advice without authority is a slide deck.
The ability. Engineers who can make new tools work inside old systems without breaking what customers rely on.
Time to select. As illiquid argues, models accelerate search far faster than the world can verify the results.7 A new price must survive a renewal season. A new contract must prove customers renew it. Someone must be able to wait for the answer, which rules out anyone working to an engagement deadline or a loan covenant.
Now look at who holds each one.
| Access | Right to actuate | Ability | Time to select | Keeps the payoff | |
|---|---|---|---|---|---|
| AI deployment company | Borrowed, for the engagement | Advisory only | Yes | Until the engagement ends | No: a fee |
| Consultancy or IT services firm | Borrowed | Advisory only | Partly | Until the engagement ends | No: a fee |
| Leveraged buyout fund | Yes | Yes | Usually hired in | Limited by debt and a fixed exit | Yes, less interest |
| The founder alone | Yes | Yes | Rarely | Yes, until retirement | Yes |
| Chroma | Yes | Yes: majority control | Yes: our own engineers | Yes: little or no debt, no fixed exit | Yes |
Only the owner holds all four. The founder lacks the ability. The deployment company lacks everything except the ability. The leveraged buyer has the authority but sells its patience to the lender. That is the gap Chroma was built to fill.
Option writers and option holders
In options markets, everyone understands the difference between the person who sells an option for a premium and the person who owns it. The seller collects a fee today. The holder keeps whatever the option turns out to be worth. The AI deployment market has quietly divided along the same line.
A simple example makes the point. The figures are our illustration, not a forecast and not a Chroma result.
Take a regional inspection company with $2.25M of EBITDA. Better routing, machine-drafted reports and a long-overdue price review lift EBITDA by $1.2M a year. Suppose a deployment firm had been hired to do the same work and charged a generous $1M for it.
| The deployment firm | The owner | |
|---|---|---|
| What it receives | A $1M fee, once | $1.2M of extra EBITDA, every year |
| What that is worth | $1M | About $7.2M of enterprise value at 6x EBITDA, before cash paid out along the way 12 |
| When the next model ships | A new engagement to sell | A free upgrade to every option it already holds |
The last row is the one that matters. Every improvement in models raises the value of the options inside a company. The labs and hyperscalers pay for that improvement, with hundreds of billions of dollars of capex.9 The owner of an instrumented business receives it for the price of an API call. Owners are long model progress without paying for the research. Service firms have to sell it again, one engagement at a time.
This is not a criticism of the deployment companies. They will do important work and some will be very good businesses. It is a statement about where the economics settle. The fee goes to whoever does the work. The compounding goes to whoever owns the company.
Where the deployment companies won't go
The new deployment companies are built for a particular customer, and it isn't the one we buy.
They are pointed at large and mid-sized companies. The Anthropic venture is starting with Blackstone's portfolio companies before expanding into the mid-market.2 OpenAI's unit is backed by some of the largest buyout firms in the world, whose own portfolios are the obvious first customers.1 Capital of $1.5–4B is built to serve clients who can sign large engagements.
A $3M-EBITDA business can't buy what they sell. It has no CIO to sponsor a project, no budget for a multi-quarter engagement, and no one to own the result after the engineers leave.
They are limited by experts. The Commanding Heights makes the point directly: deployment firms can diffuse AI only as fast as they can hire capable experts, which makes them too slow and too small for the size of the opportunity.9 Experts that scarce will be spent where the fees are largest.
So the largest pool of uninstrumented complexity in the country, the owner-run businesses below $10M of EBITDA, is also the pool the deployment boom is least likely to reach. Large capital can't buy these companies at scale either: in 2025, funds of $500M or more took about 81% of LP dollars raised.13 That leaves the options in these businesses available to an owner that brings its own engineers, at prices of about 6–7 times EBITDA.12
Consultants see the pilot. Owners see the P&L.
The most interesting idea in this debate is about learning, not deployment. illiquid argues that if the labs' deployment arms are to succeed, they need two things. First, a predictive model of which pockets of the economy produce the highest returns to intelligence, and how large those returns are. Second, a deployment meta-learner: a system that gets better at realising those returns with every deployment. The crucial link is that the second feeds the first. Every deployment produces the ground truth that makes the predictions sharper.7
We think that is exactly right, and that a services firm can only half-build it. A deployment engineer sees the pilot. They see whether the tool worked in the first quarter. They rarely see whether the price increase held through the renewal season, whether the service contracts renewed, whether the technician's freed-up hours turned into revenue, or what the business sold for. The engagement ends before the answer arrives. Their learning loop is cut off just before it closes.
An owner's loop doesn't break. We see every lever all the way through to cash, and then to the exit. That is why we report each company's results lever by lever, and why we hold one company at a time:
- Each company produces ground truth. Which processes paid back, how much, how fast, and what it took.
- The ground truth builds the map. Across companies, we learn where intelligence pays most: by process, by sector, by size of business.
- The map directs the capital. It tells us which themes to pursue and which companies to buy, the same discipline we describe in Where the Puck Is Going.
- The next company is cheaper and faster. The second pricing project reuses the first one's data. The fifth systems migration reuses the first four.
That loop is Chroma's version of the meta-learner, built with the one thing a service firm can't rent: the right to see the results all the way through. The map it produces belongs to us. The underlying records belong to the businesses and their customers. We learn from results, not by selling anyone's data.
What would prove us wrong
Deployment becomes a product. If installing intelligence inside a small business becomes as easy as buying software, the scarce ability disappears and the edge moves to sourcing and price alone.
The deployment companies come down-market and start buying. If the lab-backed services firms decide to own small businesses rather than serve them, they become well-funded competitors for the same companies. We would welcome the validation and respect the competition.
The options are worth less than we think. If the gains from pricing, routing and recurring contracts prove smaller or slower than our underwriting assumes, the payoff shrinks. That is why every deal must work on today's business, with the options as upside.
We can't hire the builders. Engineers who have rebuilt real businesses are scarce. If they won't join a small firm, the model doesn't run.
Each of these would show up early, company by company. That is by design.
Our recommendation
For allocators: the deployment boom is real, and it is being funded by some of the smartest capital in the world. The question is which side of it to own. Fees for deploying intelligence will be competed down as more engineers learn the work. The options inside companies will not be. Back the owners who hold them.
For owners: your business is full of options that have sat unexercised for decades. Before you pay someone to exercise them, ask who keeps the payoff once the engineers have gone home. If you would rather keep a share of it, roll over part of your stake with an owner who brings its own engineers.
For ourselves: a small number of companies, each with a written plan, with results reported lever by lever. Every company makes the map sharper and the next company cheaper.
The labs have spent hundreds of billions of dollars building the most powerful lever in history, and billions more hiring people to pull it on someone else's behalf.
Archimedes asked for something simpler. He didn't want a longer lever. He wanted a place to stand.
Intelligence is the lever. Ownership is the place to stand. We intend to stand there.
— Chroma Partners